
Draw up to $5M against your business cash flow, then repay and redraw as you need it. Funds land in your Rho account in as little as 24 to 48 hours after approval, with up to 180 days to repay each draw.
Rho Capital is a revolving credit line against your business cash flow, not a term loan or a venture debt facility. Rho is a fintech, not a bank. Financing offered by third parties. Rho Capital is not a broker-dealer. It does not participate in the negotiation or execution of any transactions between customers and third-party financing sources. Rho does not guarantee that the connection services will result in financing. A personal guaranty may be required, depending on underwriting. Rho is a fintech company, not a bank or an FDIC-insured depository institution. Checking account and card services provided by Webster Bank, a division of Santander Bank, N.A. Member FDIC.
What you get with Rho Capital
¹ Larger facilities considered case by case. Rho is a fintech company, not a bank or an FDIC-insured depository institution.
- 01
Apply from your Rho account
Give us the standard business details on file, your EIN, formation documents, and ownership information, along with a look at recent cash flow.
- 02
Underwriting reviews your business
We look at the shape of the business today rather than checking it against a fixed, one-size checklist. Depending on underwriting, approval may also require a personal guaranty from a business owner.
- 03
Get approved
Once approved, your line is ready. There's no separate login and no new account to manage; it lives alongside your existing Rho account.
- 04
Draw, repay, and redraw
Funds land in your Rho account in as little as 24-48 hours after approval. Repay each draw on your own schedule, up to 180 days, then draw again as you need to.
No prepayment penalties.
- Revolving working capital line of credit, up to $5M
- Funds land in your Rho account in as little as 24 to 48 hours after approval
- Repay each draw on your own schedule, up to 180 days
- No prepayment penalties on early repayment
- Runs on your existing Rho account, no separate login
Fees vary based on risk assessment and loan term, and are set when Slope underwrites your line. Your exact pricing is disclosed in your credit agreement and confirmed before you accept a line, so there are no surprises after you draw. There are no prepayment penalties, so repaying early never costs extra.
Pay now, collect later
Funds can land in 24 to 48 hours, so paying suppliers or payroll never waits on your customers.
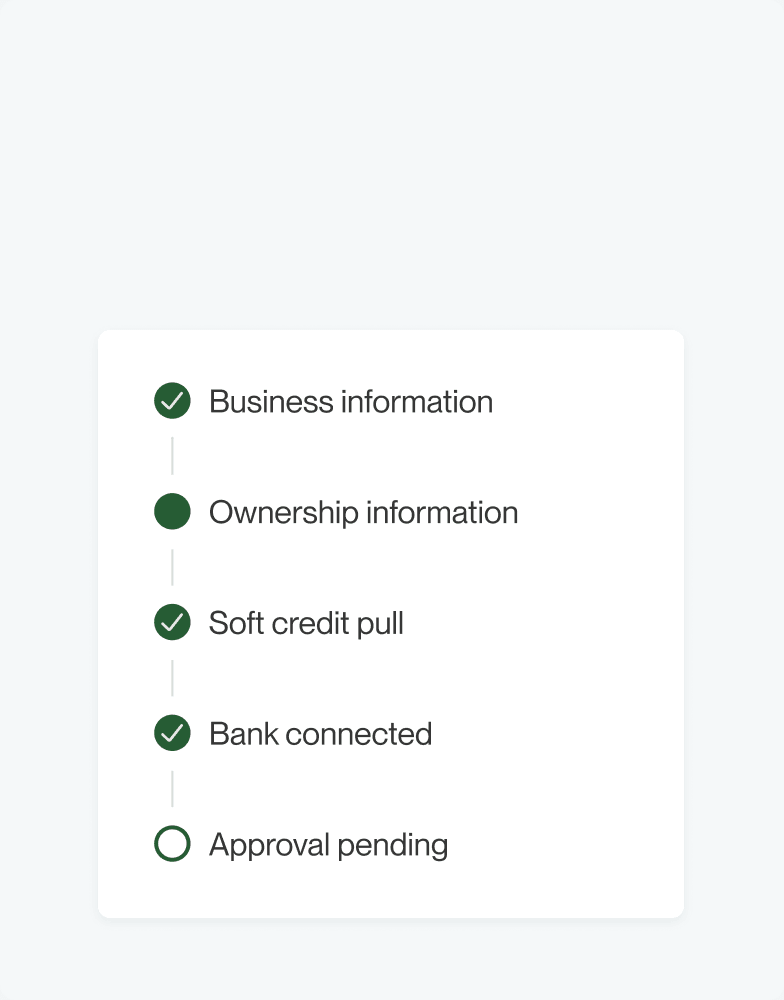
Stay in control
A short application, underwritten on your business cash flow, not your personal credit or equity.
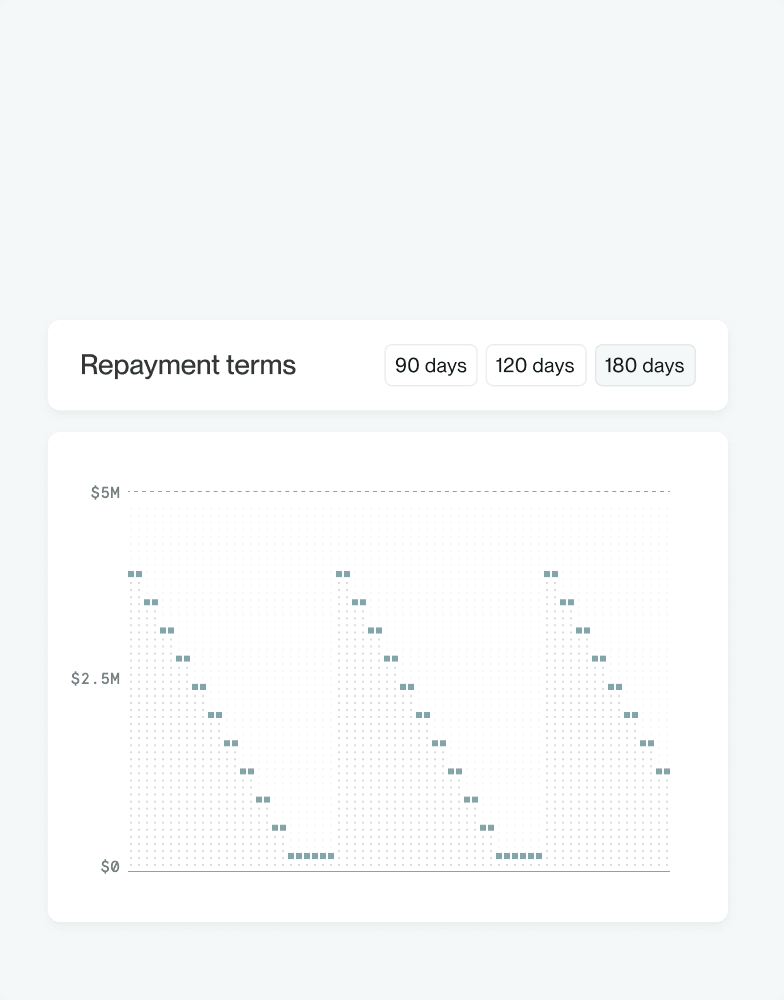
No cash flow squeeze
A revolving line with terms up to 180 days, no daily withdrawals, no revenue-share cuts, and no prepayment penalties.
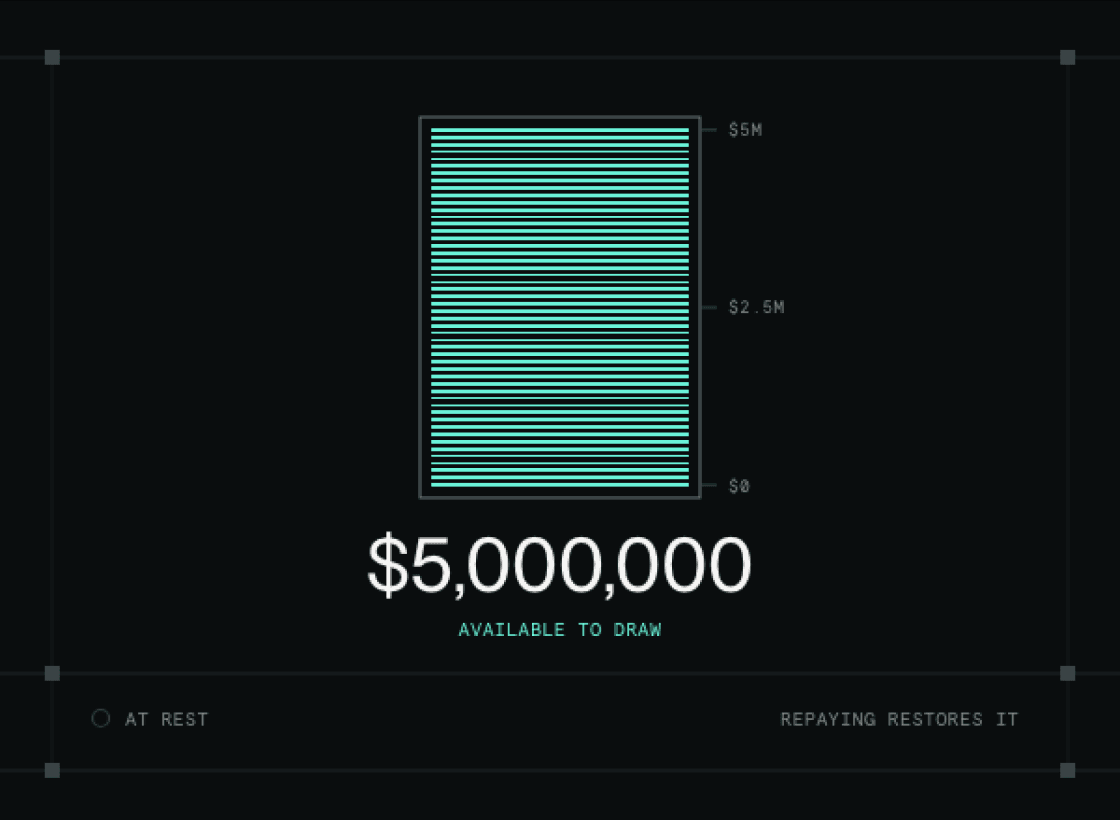
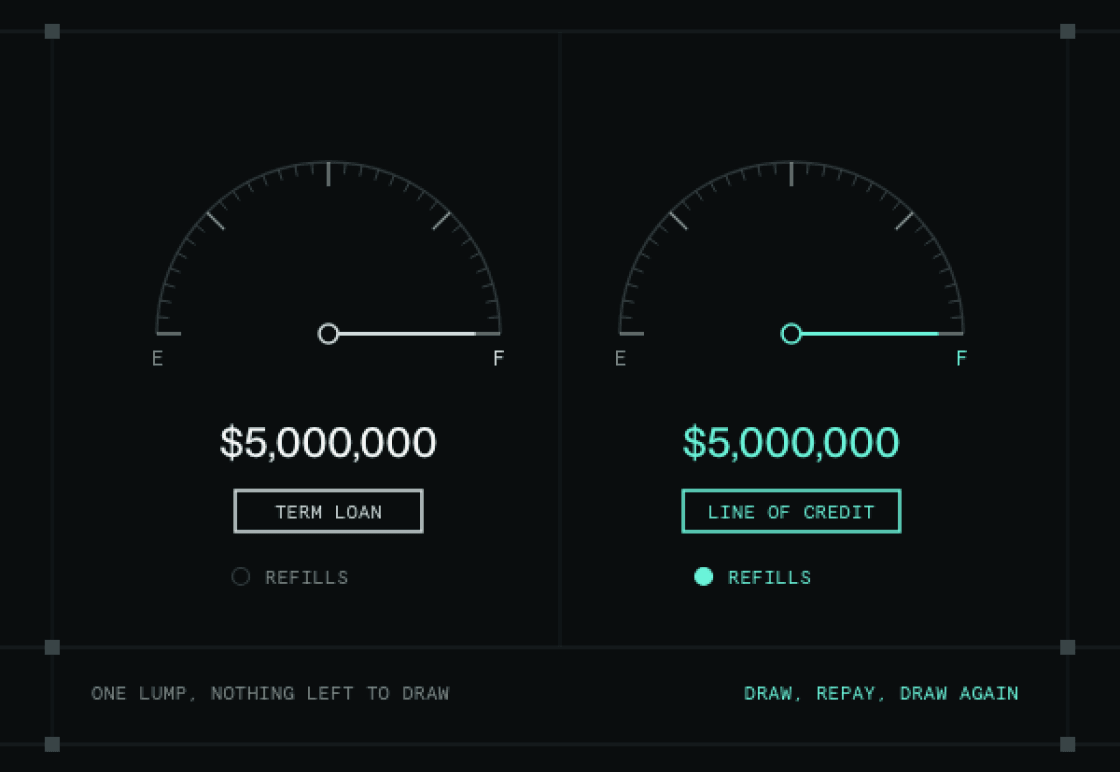
A working capital line of credit is a revolving facility: draw, repay, and redraw as cash needs shift. Rho gives qualifying startups up to $5M, funded in 24 to 48 hours after approval, with up to 180 days to repay each draw. It's one product, built into your Rho account from application through repayment.
- Draw against your approved line at any time
- Repaying restores your available credit
- Up to $5M, with larger facilities considered case by case
- Repayment terms up to 180 days per draw
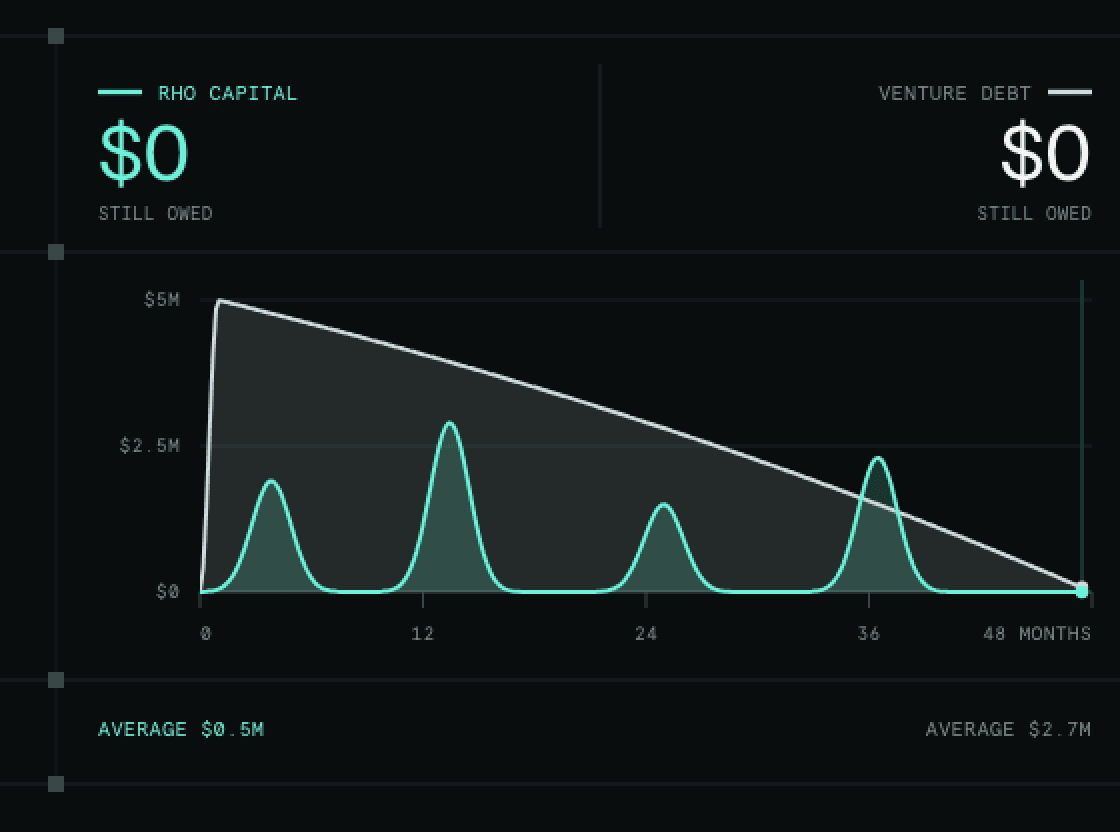
Founders often confuse the two, since both show up as "debt" options next to venture capital. The difference is what each is built to do. A working capital line of credit is short-term and operational: cover a slow month, bridge a customer payment that's running late, and it's meant to be drawn, repaid, and drawn again. Venture debt is a larger, longer facility built to extend runway alongside a funding round, and it typically comes from a specialized lender rather than a company's own bank. Rho Capital is a different product: a revolving line against your business cash flow, not a term loan or a venture-debt facility. If your business needs a fast way to smooth cash flow between now and your next invoice, a working capital line is the tool built for that. If you're extending runway around a funding round, venture debt is a different conversation, usually with your board and your preferred lenders at the table.
- Venture debt: typically a term loan structure, often with equity warrants
- Rho Capital: revolving credit line with per-draw terms up to 180 days
- Venture debt is generally sized off your last equity round; Rho Capital is sized by underwriting and not preset or guaranteed
- If you need repeatable short-cycle credit, a revolving line fits the cycle you are actually financing
Rho's working capital line of credit is evaluated through underwriting, on the shape of the business today, not a preset checklist of years in operation or a specific revenue floor. LLCs, corporations, and newer companies without years of financial history can all apply. In practice, that makes it a workable line of credit for a new business without years of financials, not just for established companies. You'll need the basics any lender asks for: an EIN, your formation documents, and details on the people who own the business. Startups that only have an EIN and no trading history yet are a common case, not an edge case. Sized by underwriting also means there's no single number that guarantees approval or rules a company out; a younger company with strong, verifiable cash flow can qualify for a meaningful line even without a long track record. Haven't incorporated yet or still waiting on your EIN? Start with <a href="/product/incorporation">Rho Incorporation</a>, then apply for Capital once you're set up.
- LLCs, corporations, and newer companies without years of financial history can all apply
- A workable line of credit for a new business without years of financials, not just for established companies
- You'll need an EIN, formation documents, and details on the people who own the business
- Sized by underwriting: no single number guarantees approval or rules a company out
Applying starts from your Rho account. You provide the standard business details on file, EIN, formation documents, ownership, along with a look at recent cash flow, and underwriting reviews the application. Once approved, the line is ready to draw against immediately. Funds land in your Rho account in as little as 24 to 48 hours after approval, and you can draw, repay, and redraw against your limit for up to 180 days per draw, without reapplying each time.
- Apply from your Rho account with your EIN, formation documents, ownership, and recent cash flow
- Underwriting reviews the application
- Once approved, the line is ready to draw against immediately
- Funds land in your Rho account in as little as 24 to 48 hours after approval
Apply from your Rho account. Approved lines fund in as little as 24 to 48 hours, with up to $5M available and up to 180 days to repay each draw.
Frequently asked questions
Yes. Most lenders evaluate an LLC the same way they evaluate a corporation: on the business's financials and history, not the entity type itself. You'll typically need your formation documents, an EIN, and details on the people who own the company. Rho's working capital line of credit is evaluated the same way, through underwriting rather than a fixed checklist.
Lenders generally look at time in business, cash flow, and existing debt obligations before extending a line of credit. Rho doesn't publish a fixed revenue or age threshold; each application is sized by underwriting, so a newer company with strong cash flow can qualify even without years of financial history.
Working capital is the cash a business has on hand to cover its near-term obligations, current assets minus current liabilities. A software company waiting 60 days to get paid on invoices but needing to make payroll every two weeks has a working capital gap. A working capital line of credit exists to bridge exactly that kind of timing mismatch.
Working capital is a measurement, the cash available to run the business day to day. A line of credit is a financial product, a revolving facility you draw against when working capital runs short. Rho's working capital line of credit is named for the problem it solves: it smooths out short-term cash gaps, not the long-term growth a term loan or venture debt is built to fund.
It depends on how the account is used. Revolving credit is typically factored into credit utilization, so drawing close to your limit or missing payments can affect a score, while a well-managed line, drawn and repaid on schedule, is often viewed favorably. This is general credit information; ask your accountant or lender how a specific facility will be reported.
For the right use case, yes. A working capital line of credit is built for short-term needs, covering payroll during a slow month, bridging a delayed customer payment, and it's usually the wrong tool for funding years of runway or a long-term capital purchase. Match the facility to the timeline of the problem it's solving.
It depends on the lender and the shape of your business. Traditional banks often want years of tax returns and a personal guarantee on the table before they'll talk. Rho's working capital line of credit is evaluated through underwriting on the financial picture as it stands today, not a rigid, one-size checklist.
The SBA's CAPLines program is a government-backed revolving line issued through a partner bank, with an SBA guarantee attached and a longer, more document-heavy approval process. Rho's working capital line of credit is a private facility with no SBA involvement, built for speed: funds can land in your Rho account in as little as 24 to 48 hours after approval, rather than the SBA's multi-week timeline.
Yes. Rho Capital is a single product: the line lives inside your Rho account from application through repayment, and funds land in that same account once you're approved.
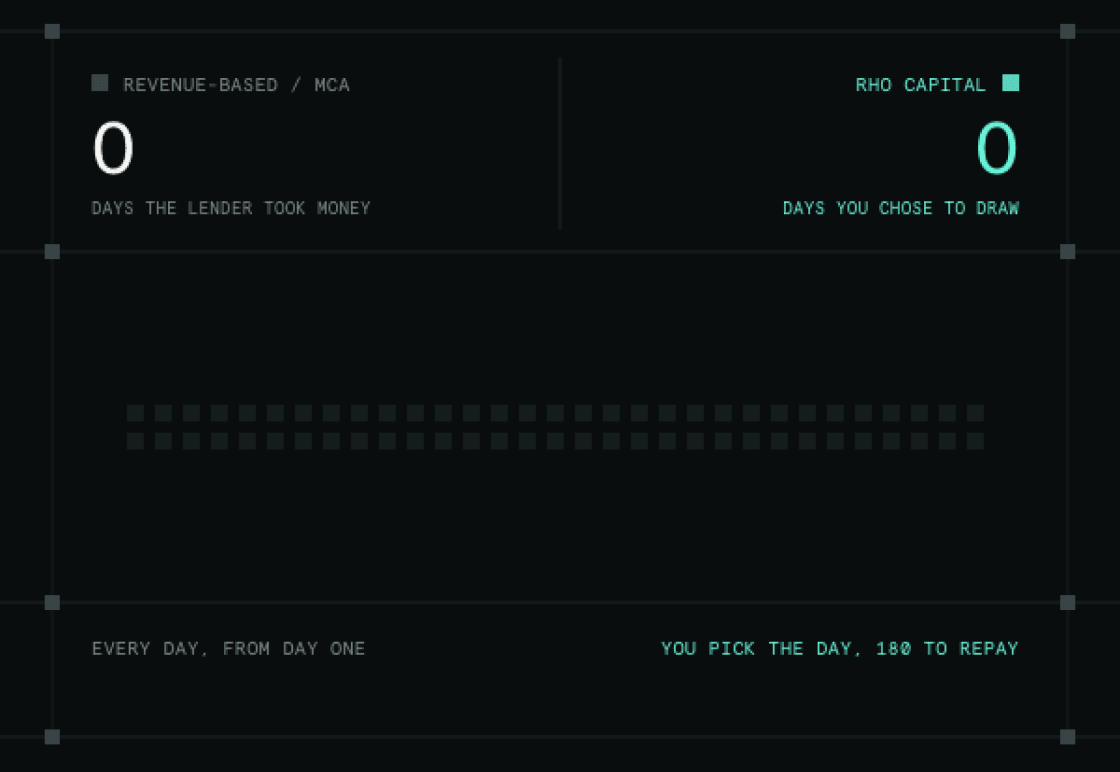
No. Rho Capital is a revolving credit line, not a merchant cash advance: no daily withdrawals and no cut of your revenue. You repay each draw on its own schedule, up to 180 days, rather than a fixed cut of daily sales.
Rho Capital is a revolving credit line against your business cash flow, not a term loan or a venture debt facility. Rho is a fintech, not a bank. Financing offered by third parties. Rho Capital is not a broker-dealer. It does not participate in the negotiation or execution of any transactions between customers and third-party financing sources. Rho does not guarantee that the connection services will result in financing. A personal guaranty may be required, depending on underwriting. Rho is a fintech company, not a bank or an FDIC-insured depository institution. Checking account and card services provided by Webster Bank, a division of Santander Bank, N.A. Member FDIC. Product claims current as of September 2026.